Holiday bookings surged at the start of January which saw holidaymakers spend roughly 5% more than last year despite finances being squeezed by the cost of living.
With the cost of bills and everyday essentials increasing, booking a holiday gives people something to look forward to and work towards but some may feel like it isn’t an option due to increased costs.
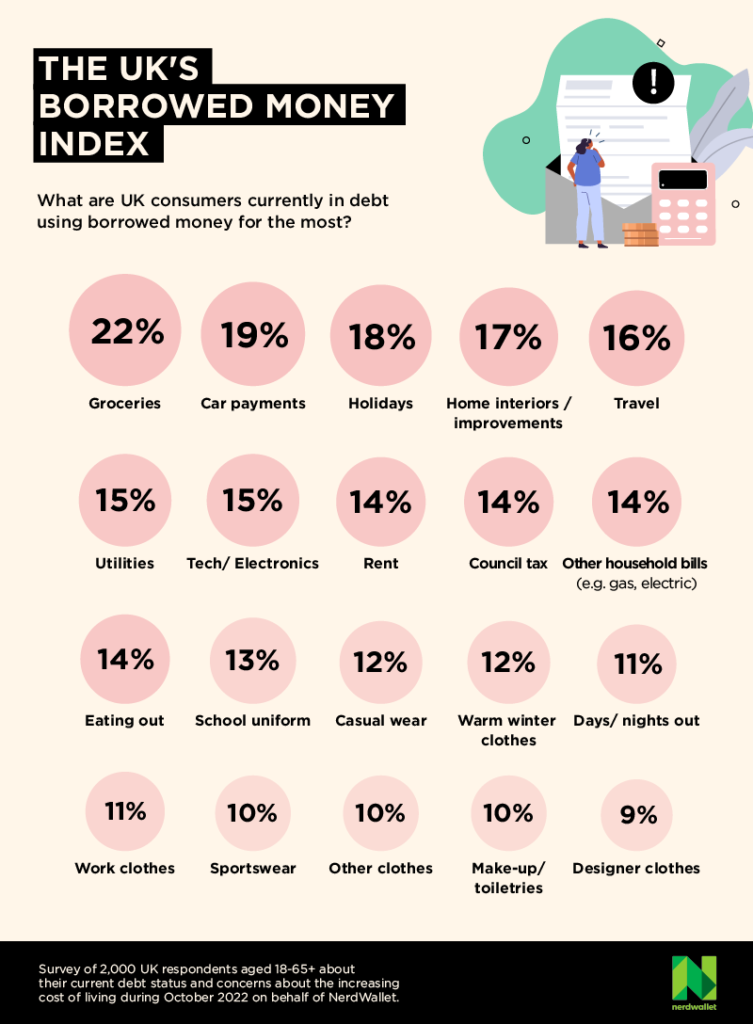
However, a recent report by the personal finance experts at NerdWallet found that 18% of Brits have used borrowed money to fund a getaway and the average time it takes to pay their debts off is 1.1 years.
This means that holiday makers will still be paying for their trip long after their tan has faded which will likely take the shine away from what was meant to be a memorable escape.
14% of respondents also admit to being in debt worth between £1,000-£5,000 and 41% worryingly believe they may need to acquire more debt to pay off their existing debt.
This suggests that holidaymakers are doing everything they can to ensure they can afford a holiday despite the economic climate as 44% of Britons admit that the cost of living crisis is their biggest concern at the moment.
The report revealed that adults aged 34-45 most commonly get into debt to pay for a holiday as 24% admit using borrowed money in this way.
It’s apparent that older adults are more likely to turn to borrowed money to help fund a holiday with 21% of 45-54 year olds and 18% of adults aged 55-64 stating they’ve used their debt in this way.
In comparison, only 13% of 18-24 year olds and 16% of 25-34 year olds have gotten into debt to fund a holiday.
Further information on the Household Debt Report can be found here, and a press release on the report can be found below.